The evolution of the financial landscape in Liberia represents one of the most critical frontiers for economic development in the post-conflict era. For decades, the reliance on traditional brick-and-mortar banking systems left the vast majority of the Liberian populace financially excluded, trapped in a cash-based economy that hindered savings, credit acquisition, and long-term investment. However, the rapid proliferation of mobile money over the last decade has fundamentally altered this narrative. As a platform for financial innovation, mobile money has moved beyond simple person-to-person transfers to become a primary engine for financial inclusion, bridging the gap between the unbanked rural population and the formal financial ecosystem.
According to data from the Central Bank of Liberia, mobile money subscribers skyrocketed from approximately 38,000 in 2013 to over 1.5 million by 2020. This trajectory is not merely a statistical curiosity; it is a profound economic signal that Liberia is ripe for digital transformation. Despite this impressive growth, the journey toward comprehensive financial inclusion remains fraught with structural and systemic obstacles.
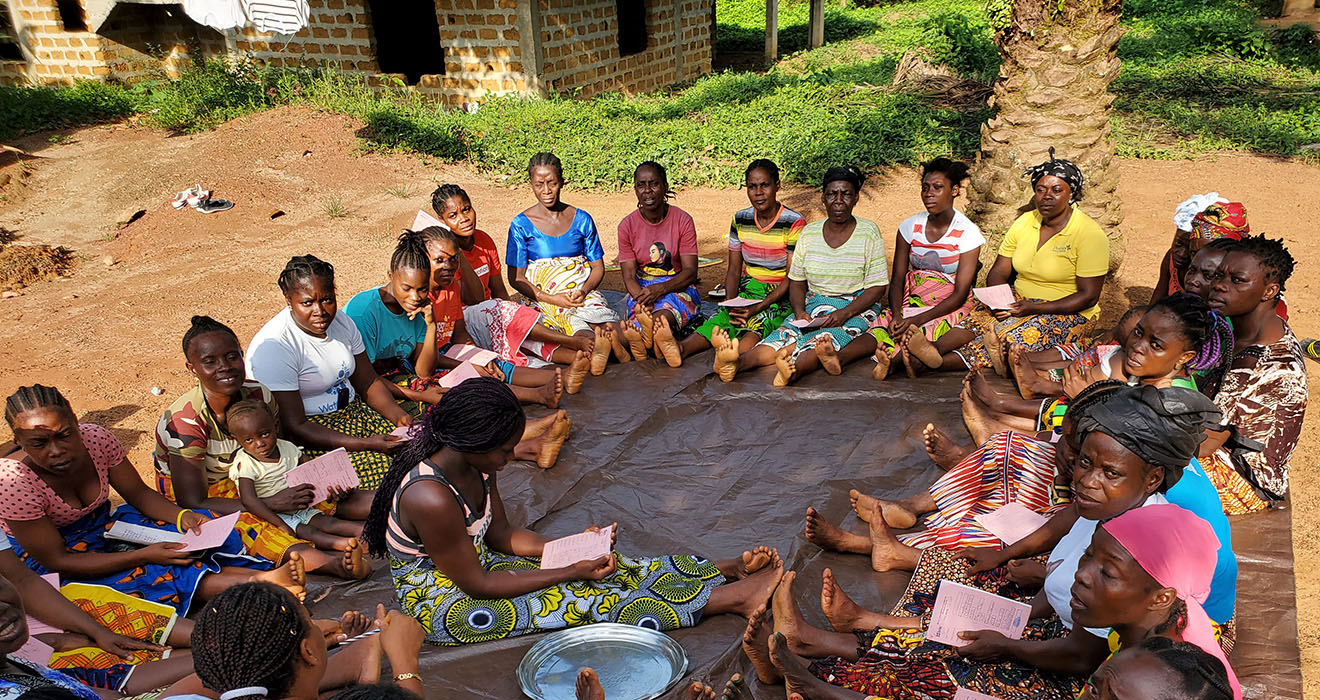
To understand the true potential of this technology, one must look closely at the interplay between infrastructure, literacy, and the regulatory environment. The primary advantage of mobile money lies in its ability to circumvent the logistical limitations of traditional banking. In a country where road networks can be arduous and the density of physical bank branches is concentrated almost exclusively in the Monrovia metropolitan area, mobile money acts as a catalyst for connectivity. It allows a farmer in Lofa County or a trader in Grand Kru to engage in secure financial transactions without the need for a physical bank account.
For these populations, remittances—funds sent by family members from urban centers or abroad—are a critical safety net. Mobile money ensures these funds arrive instantaneously, reducing the risks of cash transit and the high fees often associated with informal courier services. Moreover, the capacity for mobile money to serve as a gateway to savings and micro-credit products represents a significant opportunity for household-level economic development. When individuals can safely store money and build a transaction history, they create a 'digital footprint' that financial institutions can eventually use to evaluate creditworthiness.
This is the cornerstone of moving millions of Liberians from a subsistence-level existence into the formal economy. However, the rapid expansion of these services has not been without significant friction. The obstacles currently hindering the total integration of mobile money into the Liberian economy are multifaceted. Central among them is the digital divide.
Low levels of digital literacy, coupled with persistent gaps in formal education, mean that many potential users view mobile platforms with skepticism or struggle to navigate the user interfaces required for complex financial operations. This is compounded by the lack of robust telecommunications infrastructure. While mobile phone ownership is relatively high—exceeding 50% of the population—reliable data connectivity and stable electricity remain luxuries in many rural districts. Without consistent power and internet coverage, mobile money agents are unable to maintain liquidity or perform real-time transactions, directly undermining the reliability that is essential for consumer trust.
Security is another paramount concern. As transaction values climb—having surged from a mere $100,000 in 2012 to over $1 billion by 2020—the sector has increasingly become a target for fraudulent activities. Instances of phishing, social engineering, and unauthorized agent behavior pose serious threats to public confidence. When a user loses a significant portion of their savings to a security breach, the reputational damage to the mobile money ecosystem is profound, often driving people back to the perceived safety of hidden cash.
Addressing these challenges requires more than just technological upgrades; it requires a concerted policy shift. A comprehensive strategy must include targeted digital literacy programs aimed at marginalized communities, ensuring that women, rural farmers, and small-scale traders understand how to safely utilize digital tools. Furthermore, the government and the Central Bank must prioritize the strengthening of regulatory frameworks. Consumer protection laws must be updated to address the unique nature of digital transactions, ensuring that users have clear recourse in the event of fraud or system failure.
Public-private partnerships are also essential. Mobile network operators, commercial banks, and fintech startups should collaborate to create interoperable systems, allowing for seamless transfers between different platforms and traditional bank accounts. By lowering the barriers to entry, such collaborations can foster a more competitive and efficient market. The statistical reality of Liberia’s financial environment is stark.
The World Bank and Global Findex reports consistently highlight that roughly 64% of Liberian adults remain unbanked. With only 13% of the population holding a formal bank account, the dependence on cash-only systems leaves a vast majority of the population vulnerable to theft and excluded from the benefits of interest-bearing accounts or institutional lending. The mobile money sector provides the only scalable solution to these pervasive issues. Looking at the success stories of other African nations, such as Kenya with its M-Pesa model or Uganda’s mobile-driven banking revolution, the lesson is clear: when the regulatory environment is supportive and the technology is accessible, financial inclusion is not just a dream but an inevitable outcome.
In these nations, mobile money served as the foundation for broader financial services, including micro-insurance and mobile-based credit, which empowered SMEs to expand their operations. Liberia stands at a similar crossroads. The potential is immense, but it will not be realized through passive growth. It requires proactive investment in the 'last mile' of telecommunications infrastructure to ensure that rural areas are not left in the dark.
It necessitates the integration of mobile money into government-to-person (G2P) payment schemes, such as salary payments for civil servants or social welfare disbursements. By digitizing these payments, the government can stimulate transaction volumes, encourage widespread adoption, and reduce the corruption often associated with physical cash handling. Ultimately, the future of the Liberian economy is inherently digital. Mobile money is not merely a tool for convenience; it is a vital instrument for economic resilience.
By bridging the gap for the unbanked and underbanked, Liberia can tap into the dormant economic potential of its population. The path forward involves a triple-pronged approach: investing in connectivity, fostering literacy, and enforcing a regulatory framework that prioritizes the user. If these elements are aligned, the digital financial revolution will move past the initial surge of adoption and settle into a sustainable, long-term driver of economic prosperity. The journey of the last decade has proven that Liberians are eager to embrace digital solutions; the challenge now rests with policymakers and financial institutions to build the framework that makes such participation safe, inclusive, and transformative.
As the global financial architecture continues to digitize, Liberia cannot afford to be a bystander. The transition to a mobile-first financial economy is the most viable path toward national development, providing the necessary liquidity and transparency to catalyze private sector growth and secure the financial future of every Liberian citizen.